How Long Are Rv Loans
There’s something genuinely enjoyable about the idea of hitting the open road with your home trailing behind you. Whether it’s the promise of weekend mountain getaways or the...
There’s something genuinely enjoyable about the idea of hitting the open road with your home trailing behind you. Whether it’s the promise of weekend mountain getaways or the practicality of a mobile base for remote work, RV life has a broad appeal. For many, the biggest hurdle isn’t choosing the rig—it’s figuring out the financing. Understanding how long RV loans typically last is the key to making that dream a comfortable reality, not a financial burden. The main purpose of knowing these terms is simple: it lets you match your monthly budget to your lifestyle, whether you’re a retiree planning a long, slow tour or a young family wanting a summer escape.
RV loans aren’t one-size-fits-all. Most lenders offer terms that range from 10 to 20 years, but they can stretch as long as 25 or even 30 years for higher-priced motorhomes. A common variation you’ll see is the split between a travel trailer and a Class A motorhome—the former might get a 10- or 15-year loan, while the latter often qualifies for a 20-year term. For example, a couple buying a used camper van might opt for a 7-year loan to pay it off quickly, whereas a full-time family on a luxurious diesel pusher could choose 25 years to keep monthly payments low.
The beauty of longer loan terms is that they lower your monthly payment, making a big purchase feel more accessible. However, there’s a trade-off: you’ll pay more in interest over the life of the loan. A 30-year RV loan might sound sweet for your cash flow, but the total cost can be eye-opening. For instance, a $50,000 RV at 7% interest over 10 years costs about $580 per month and roughly $19,500 in total interest. Stretch that to 20 years, and the payment drops to $387, but the interest nearly doubles to $43,000. That’s a practical lesson in balancing present ease with future cost.
Must Read
Your specific situation heavily influences what loan length makes sense. Retirees often prefer shorter terms (10–15 years) to own the RV free and clear before their income changes. Young professionals might lean toward 20-year loans to keep payments manageable alongside rent or a first mortgage. A key rule of thumb? Never let the loan term exceed the useful life of the RV. Most RVs depreciate quickly, so financing a 30-year loan on a 10-year-old used rig means you could owe more than it’s worth before you’ve even hit the road.
To get started, check your credit score first—the best rates go to scores above 700. Then, shop around with banks, credit unions, and specialized RV lenders. A credit union often offers the most competitive rates, especially for members. Before signing, ask the lender for a clear amortization schedule that shows how much goes to principal versus interest each year. Also, consider making a larger down payment (20% or more) to reduce the loan amount needed, which can shorten the ideal term and save you thousands.
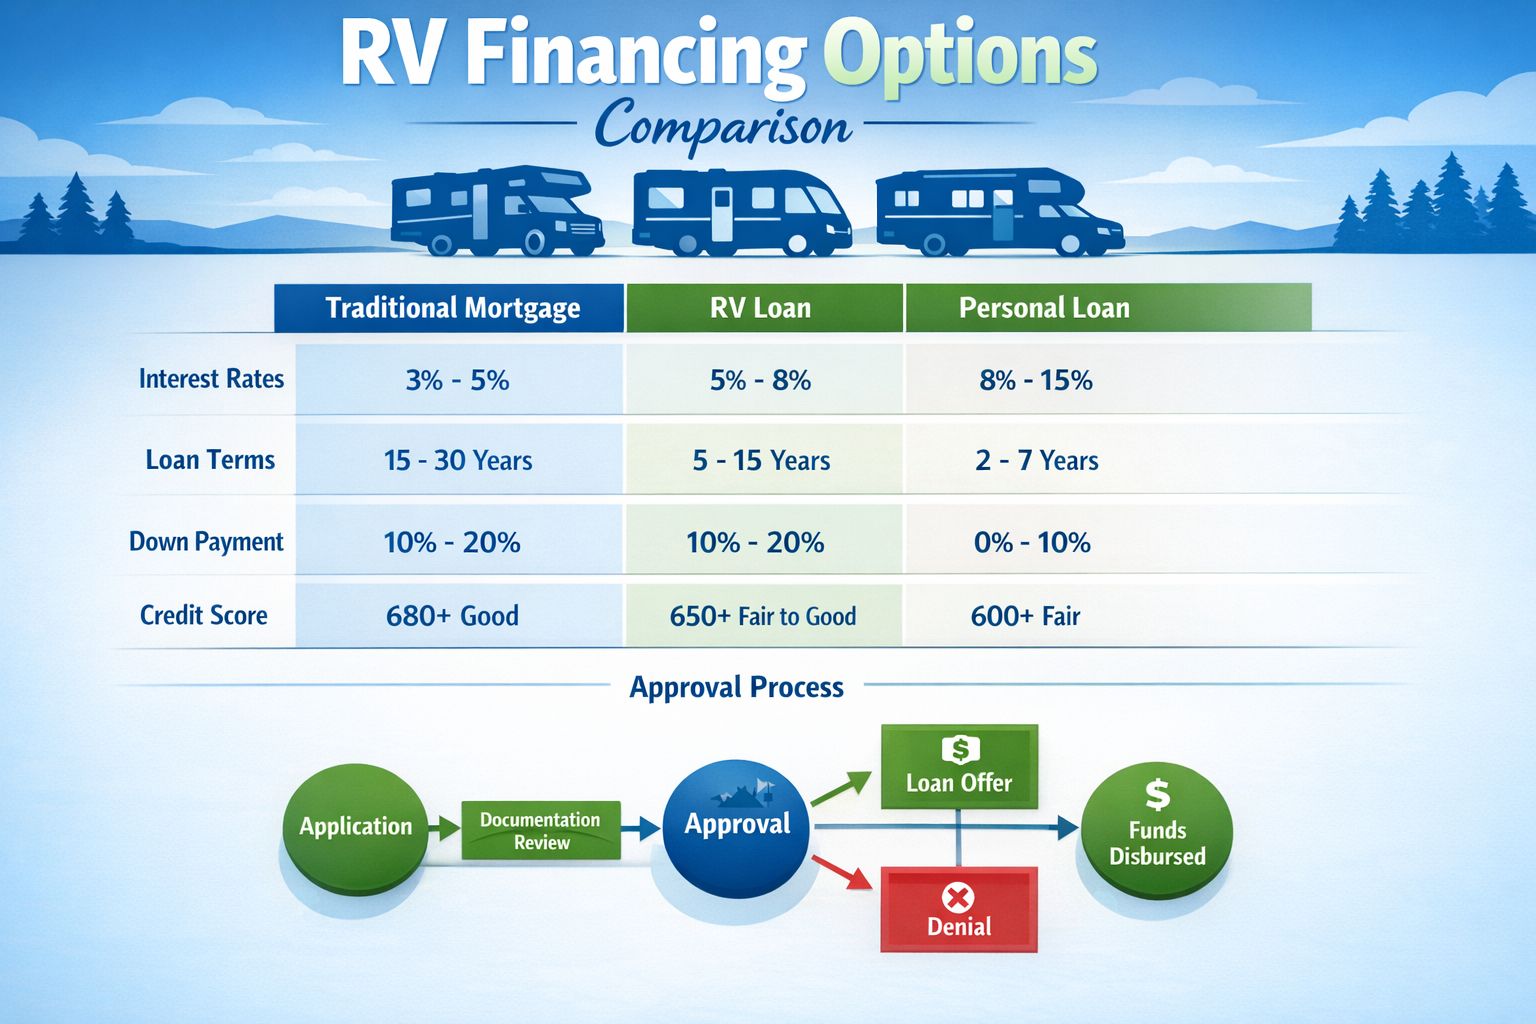 Can You Get a Mortgage on an RV? Complete 2026 Financing Gu
Making the most of an RV loan means matching the term to your travel habits. If you plan to keep the RV for a decade, a 10-year loan is your sweet spot—you’ll build equity fast. If you’re unsure, a 15-year term is a popular compromise, offering a reasonable payment without locking you into decades of debt. And remember, you can always pay extra when you have spare cash—most RV loans don’t have prepayment penalties, so you can shorten the term on your own schedule.
Ultimately, the length of your RV loan should support your journey, not define it. By understanding the trade-offs between monthly ease and long-term cost, you can choose a term that lets you savor every campsite—without the financial headache. So dream big, but do the math, and hit the road with confidence.


