How Many Years Are Rv Loans
For countless individuals and families, the open road represents the ultimate escape. The ability to pack up life’s essentials and chase a sunrise over a national park or a co...
For countless individuals and families, the open road represents the ultimate escape. The ability to pack up life’s essentials and chase a sunrise over a national park or a cozy campsite by the lake is a deeply cherished dream. At the heart of this freedom is the recreational vehicle, a mobile home that brings adventure to your doorstep. But for many, the question isn’t just “Can I afford it?” but “How many years can I take to pay it off?” Understanding RV loan terms is the first step to turning that weekend fantasy into a sustainable reality.
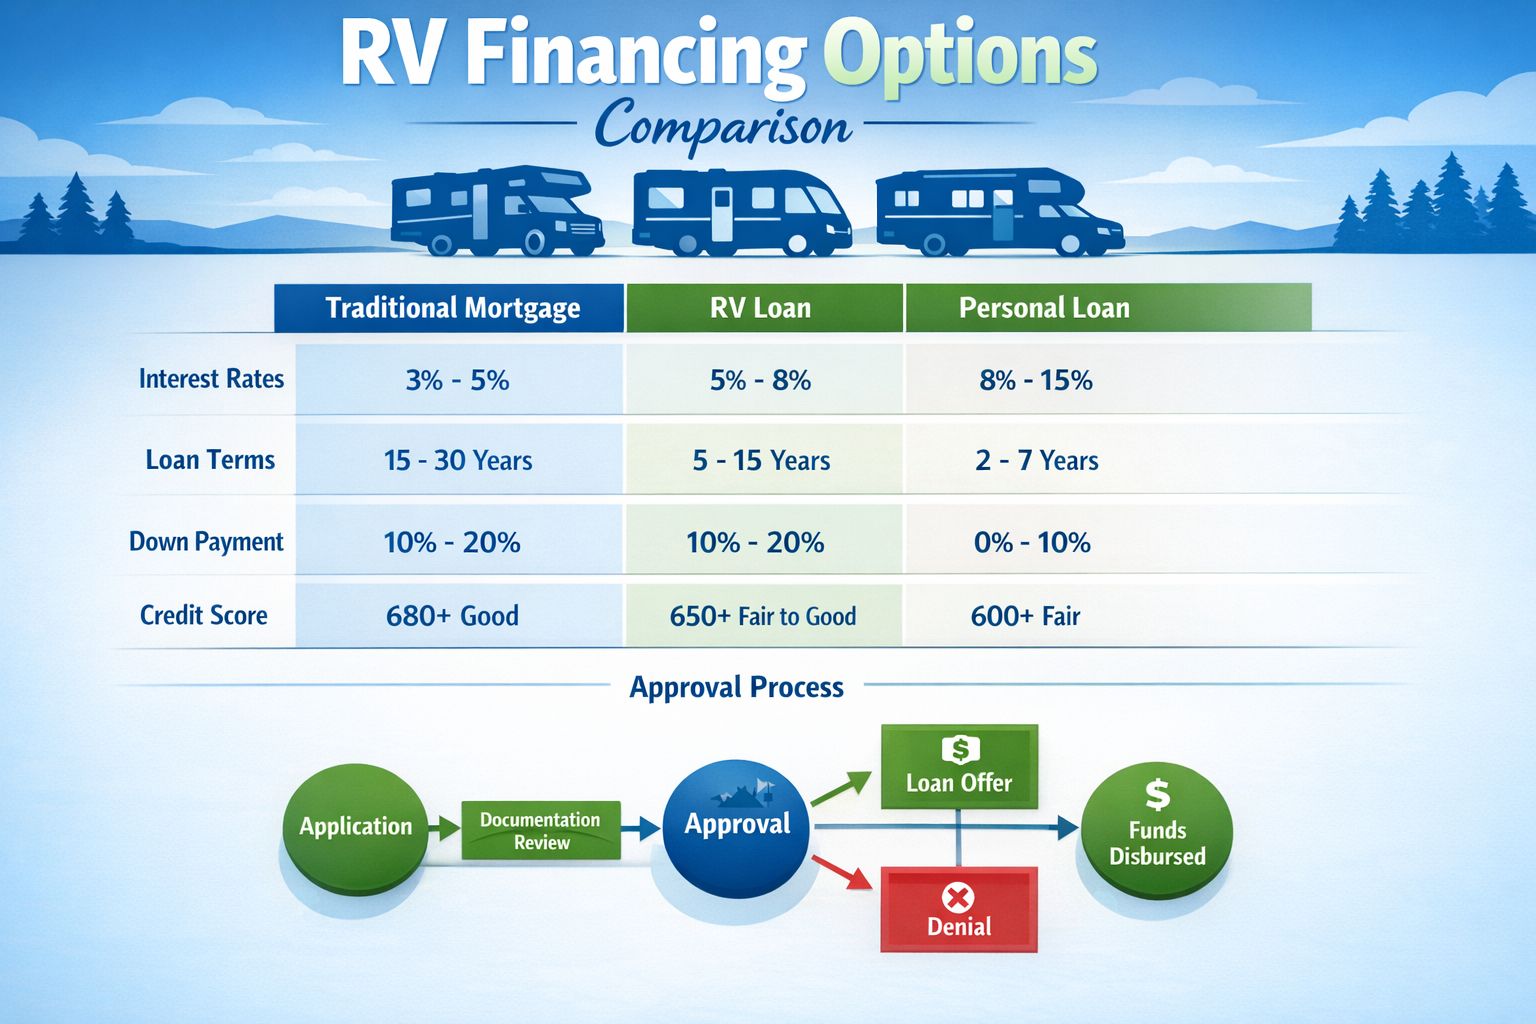
The key purpose of an RV loan is to make a large purchase manageable by spreading the cost over a set period, much like a car or home loan. Unlike a standard car loan, however, RV terms are notably longer because the vehicle itself has a longer usable life. A typical RV loan can range from 10 to 20 years, though terms as short as 5 years or as long as 25 years are available depending on the lender and the type of RV. This flexibility is a major benefit for daily life, allowing you to budget a predictable monthly payment without sacrificing other financial goals.
Consider a scenario: a young couple buys a used travel trailer for $30,000. They might opt for a 10-year loan to keep payments lower while still paying off the vehicle before it ages too much. In contrast, a family purchasing a brand-new Class A motorhome for $150,000 might prefer a 20-year term. This longer duration reduces the monthly payment from roughly $2,000 (on a 7-year loan) to about $1,100, freeing up cash for fuel, campground fees, and maintenance. The choice directly impacts the affordability of the lifestyle.
Must Read
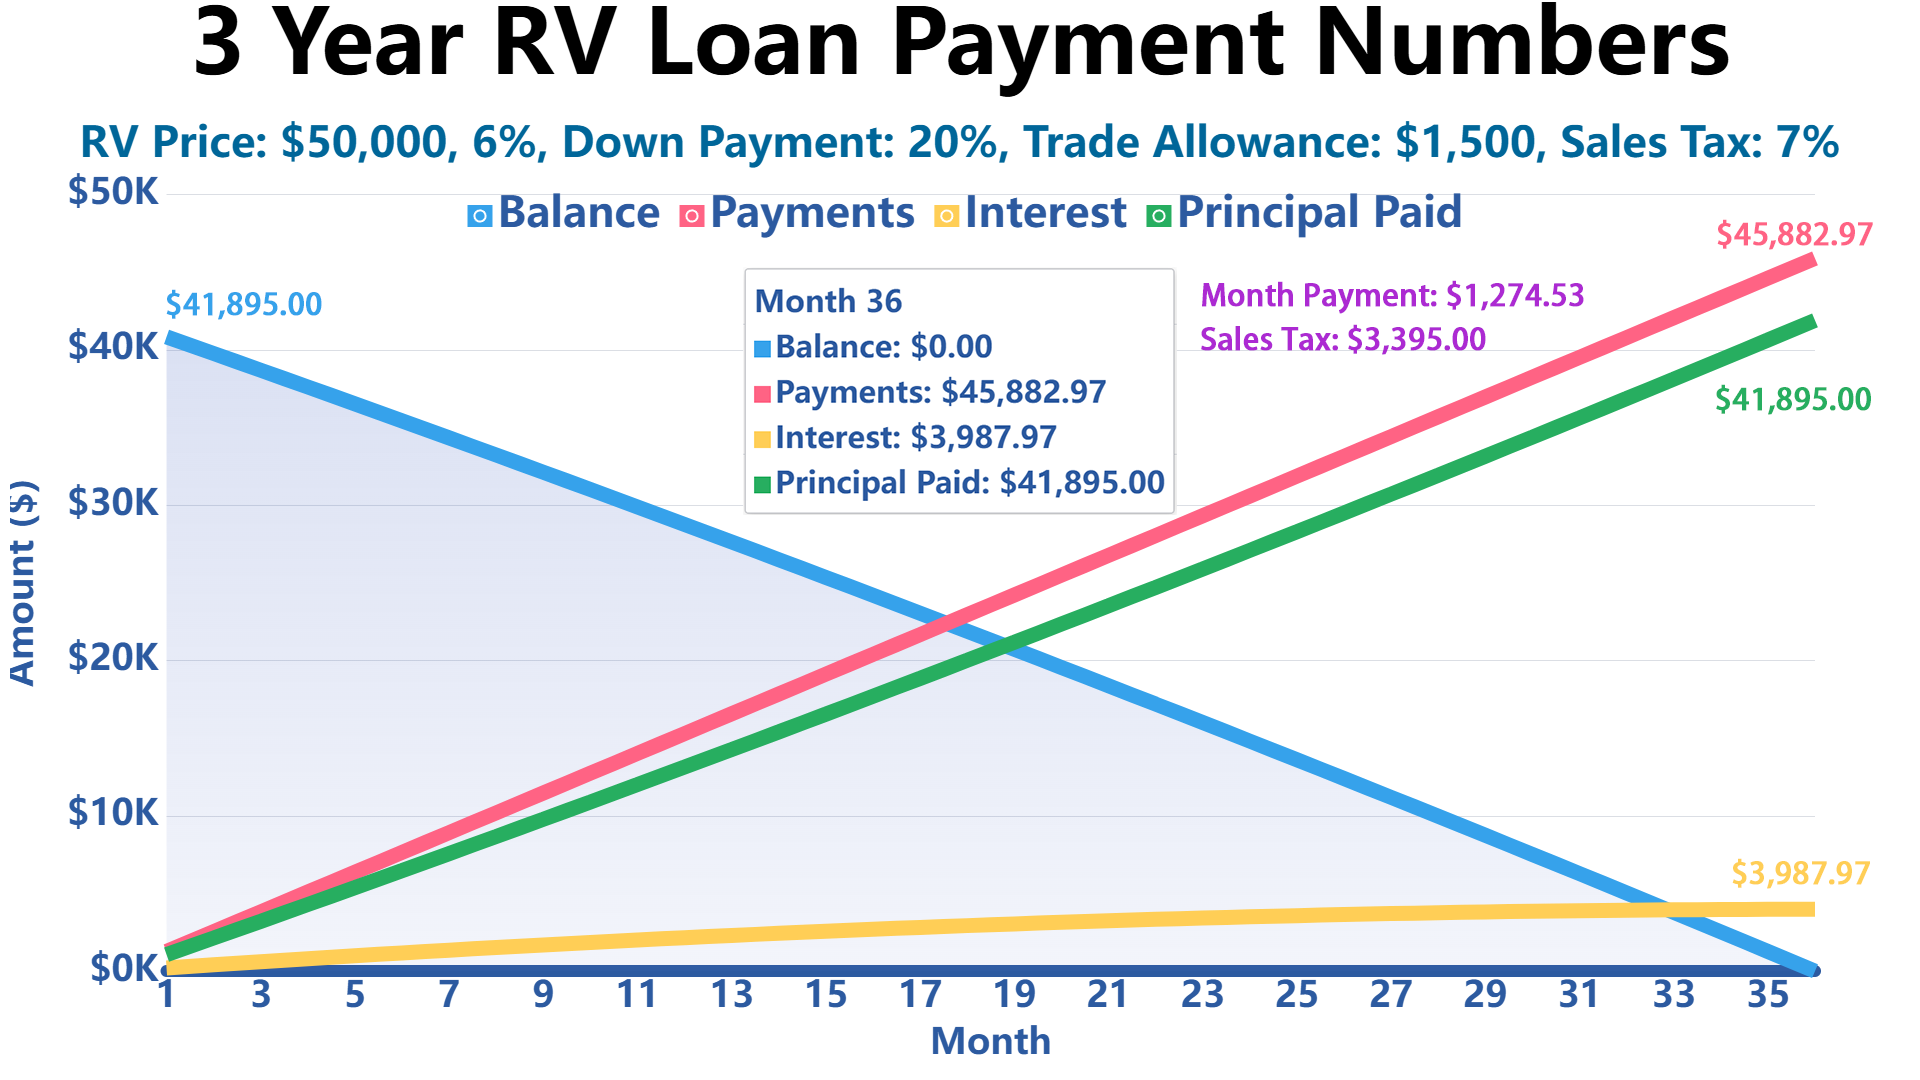
However, the length of your loan has significant trade-offs. A shorter term, such as 5 to 10 years, means you pay less interest overall and build equity faster. A longer term, like 15 to 20 years, offers lower monthly payments but can double the total cost of the RV due to accumulated interest. For example, a $50,000 RV at 7% interest over 10 years costs roughly $69,000 total, while the same RV over 20 years balloons to over $93,000. This is why interest rates and total loan cost are critical to evaluate.
For everyday life, the benefits of a well-chosen loan term are clear. It allows you to align your payments with your income, avoid financial strain, and still enjoy spontaneous weekend getaways. Imagine taking a month-long summer road trip with your kids because your monthly RV payment is affordable—that is the real value of a properly structured loan. Without this flexibility, the dream can quickly become a burden.
 RV Market Outlook 2024 - National Vehicle
To explore this on your own, start by shopping around. Contact banks, credit unions, and specialized RV lenders to compare rates and terms. Credit unions often offer the best rates for longer terms. Use an online loan calculator to see how different years (10, 15, 20) change your monthly payment and total interest. Finally, never borrow for more years than you intend to keep the RV; a 20-year loan is risky if you might sell the vehicle in 7, as you could owe more than it’s worth.
In the end, how many years an RV loan lasts is a personal decision rooted in your budget, travel dreams, and financial discipline. Whether you choose a brisk 7-year sprint or a leisurely 20-year cruise, the goal remains the same: to unlock the open road without locking yourself into debt. With careful planning, you can drive off confident that your adventure is built on a solid foundation.